Get professional assistance with charitable organisation registration and tax-related compliance through Enreta.
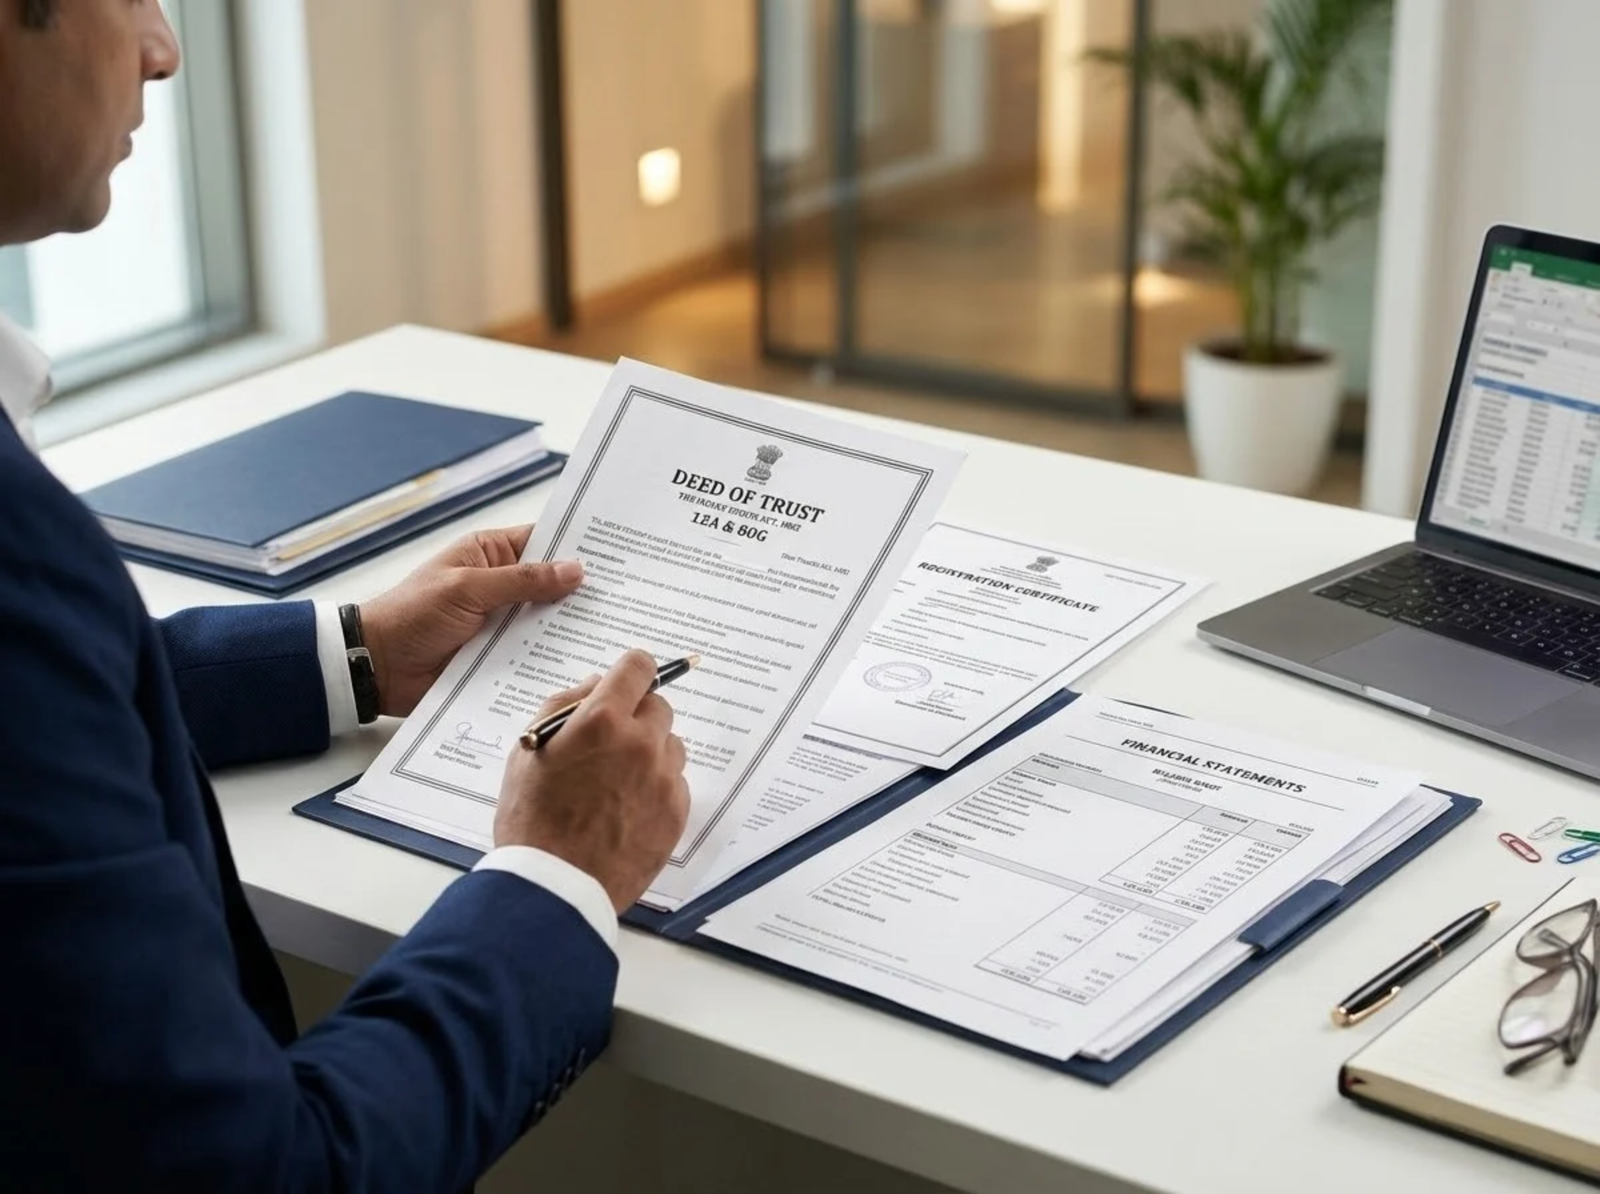
Build a stronger foundation for your charitable organisation with professional 12A and 80G registration assistance from Enreta. Whether you are establishing a new NGO or managing an existing charitable trust, we help you understand the applicable tax requirements, prepare essential documentation and navigate the application process with greater confidence.
Running a charitable organisation involves more than serving the community. It also requires appropriate documentation, financial transparency and compliance with applicable tax regulations. The relevant income-tax registration and approval can play an important role in helping eligible organisations manage their tax obligations and establish credibility with potential donors.
At Enreta, we help eligible NGOs, public charitable trusts, registered societies and Section 8 companies understand the requirements applicable to their organisational structure. From reviewing governing documents to preparing application information, our assistance is designed to make the process more organised and easier to navigate.
A well-organised document set can make application preparation easier. Depending on your organisation and application category, you may need:
Organisation PAN and registration certificate.
Trust deed, memorandum, rules or other governing documents.
Details of trustees, directors or authorised representatives.
Registered office address details.
A clear description of charitable objectives and activities.
Financial statements and relevant income and expenditure records, where applicable.
Details of existing registrations, approvals and previous applications.
Other declarations and supporting documents required under the applicable procedure.
The exact list should be confirmed before filing because requirements may differ for new organisations, established institutions and existing registration holders.
An NGO may receive donations subject to applicable laws and its legal status. However, donors generally cannot claim a deduction under Section 80G merely because the organisation is charitable; the required approval and other conditions must be satisfied.
No. The deduction depends on the organisation’s approval status, the nature and mode of donation, applicable limits and the donor’s eligibility. Donations in cash above the prescribed limit and donations in kind are subject to specific restrictions.
An eligible organisation can use its registration details when communicating its compliance status to potential donors. However, it must represent its registration accurately and comply with the conditions attached to its applicable approvals.
Changes to an organisation’s objects may affect its existing registration or approval obligations. The organisation should review its governing documents and determine whether an application or intimation is required under the applicable tax provisions.
The applicable process depends on the organisation’s circumstances, existing registration status and current rules. The relevant application requirements should be checked for each registration or approval rather than assuming one automatically covers the other.
The applicable route may differ for a newly established organisation and one that has already commenced activities. Eligibility and the required application category should be assessed according to the organisation’s circumstances and current rules.
WhatsApp us